Abstract
European Union law has long regulated consumer protection by reference to the concept of the average consumer, who is presumed to be reasonably well-informed, reasonably observant and circumspect. However, research into bounded rationality and cognitive biases demonstrates that the way in which choices are presented can significantly influence decision-making. From dark patterns to the Compass Banca case, EU law is increasingly concerned not only with the information made available to consumers, but also with the circumstances in which they are required to make decisions.
What does it mean to be an “average consumer”?
When an advertisement, commercial offer or particular sales practice is subject to scrutiny by a regulatory authority or court, it is not always feasible to examine how each individual consumer has responded. Consumers differ in their knowledge, experience, levels of attention and understanding.
For this reason, European Union law has long relied on an abstract legal benchmark: the “average consumer”.
Recital 18 of Directive 2005/29/EC concerning unfair business-to-consumer commercial practices defines the relevant benchmark as a consumer who is “reasonably well-informed and reasonably observant and circumspect”, taking into account social, cultural and linguistic factors. The Directive also makes an important clarification that is frequently overlooked: the average consumer is not a statistical measure. Rather, national courts and authorities must determine, on a case-by-case basis, the likely reaction of a typical consumer in the circumstances under consideration.
The average consumer benchmark enables commercial practices to be assessed without reconstructing the individual responses of every person exposed to them. However, the assessment must also take account of the audience actually targeted or reached by the practice. Where the conditions laid down in Article 5(3) of the Directive are satisfied, practices affecting a particularly vulnerable group of consumers, for example by reason of age or credulity, must be assessed from the perspective of the average member of that group.
Moreover, being reasonably observant and circumspect does not imply immunity from cognitive influences.
Historically, the consumer’s ability to make informed choices has been safeguarded primarily through information disclosure requirements. Before entering into a contract, consumers must be informed of the characteristics of the service, its price, duration, payment arrangements and any applicable right of withdrawal. This approach is reflected, for example, in Article 49 of the Italian Consumer Code, which governs pre-contractual information requirements for distance contracts.
Yet, having access to information does not necessarily mean that consumers will read or understand everything provided to them. A study conducted for the European Commission on online terms and conditions found that many consumers tend to accept contractual terms without reading them, while shorter and simpler texts improve their accessibility and usability.
It is precisely this limitation that behavioural sciences seek to address. The Organisation for Economic Co-operation and Development (OECD) has highlighted how information overload, cognitive limitations and the manner in which information is presented may undermine the effectiveness of disclosure requirements. Consequently, merely making information available to consumers may not, in itself, be sufficient to ensure genuinely informed decision-making (see Improving Online Disclosures with Behavioural Insights, OECD).
How rational are we when making decisions?
The challenge to the assumption that human beings are perfectly rational decision-makers is by no means new.
One of the scholars who contributed most significantly to this shift in perspective was Herbert Simon, the American economist and psychologist awarded the Nobel Prize in Economic Sciences in 1978 for his research into decision-making processes within economic organisations.
Simon developed the concept of bounded rationality. Its underlying premise is relatively straightforward: when making decisions, individuals do not have unlimited time, information or cognitive resources at their disposal. Rather than systematically evaluating every possible alternative until identifying the mathematically optimal solution, they make decisions within the constraints under which they operate.
Subsequent research by Daniel Kahneman and Amos Tversky demonstrated that individuals frequently rely on mental shortcuts, known as heuristics, which facilitate rapid decision-making but may also give rise to systematic errors, commonly referred to as cognitive biases.
We have previously examined some of these mechanisms in our article “Writing to Persuade: AIDA and the Copywriter’s Shortcuts”, focusing in particular on the distinction between automatic and deliberative cognitive processes and the role of mental shortcuts in persuasive communication.
For present purposes, however, a different implication of this research is particularly relevant: a decision may be influenced even in the absence of false or misleading information.
One particularly well-known example is the framing effect, investigated by Amos Tversky and Daniel Kahneman. This phenomenon describes how identical information may lead to different evaluations and choices depending on the way in which it is presented.
For example, stating that a medical treatment has a 90% survival rate or a 10% mortality rate conveys precisely the same statistical information. Nevertheless, the way in which that information is framed may alter the perception of risk and influence the resulting decision.
Beyond framing, several other cognitive phenomena may affect individual decision-making.
The status quo bias, for instance, refers to the tendency to favour existing circumstances over change, even when adopting an alternative course of action might prove beneficial. This mechanism may explain why individuals continue paying for subscriptions they rarely use, simply because cancellation requires them to take affirmative steps.
The anchoring effect, by contrast, occurs when an initial piece of information establishes a reference point against which subsequent evaluations are made. For example, an initial price of €200 may make a subsequent offer of €120 appear particularly attractive, even where the original price was deliberately introduced to influence perceptions of value.
Finally, loss aversion describes the tendency to perceive losses as more significant than gains of equivalent value. Accordingly, the psychological impact of losing €50 may be greater than the satisfaction derived from gaining the same amount, with consequential effects on economic and purchasing decisions.
These mechanisms do not suggest that consumers are incapable of making rational choices. Rather, they demonstrate that the context in which a decision is made may influence its outcome.
This becomes particularly significant in digital environments, where decision-making processes are structured through interfaces, buttons, colours, the sequencing of information and procedures that may be more or less straightforward to complete.
What happens when design influences consumer choice?
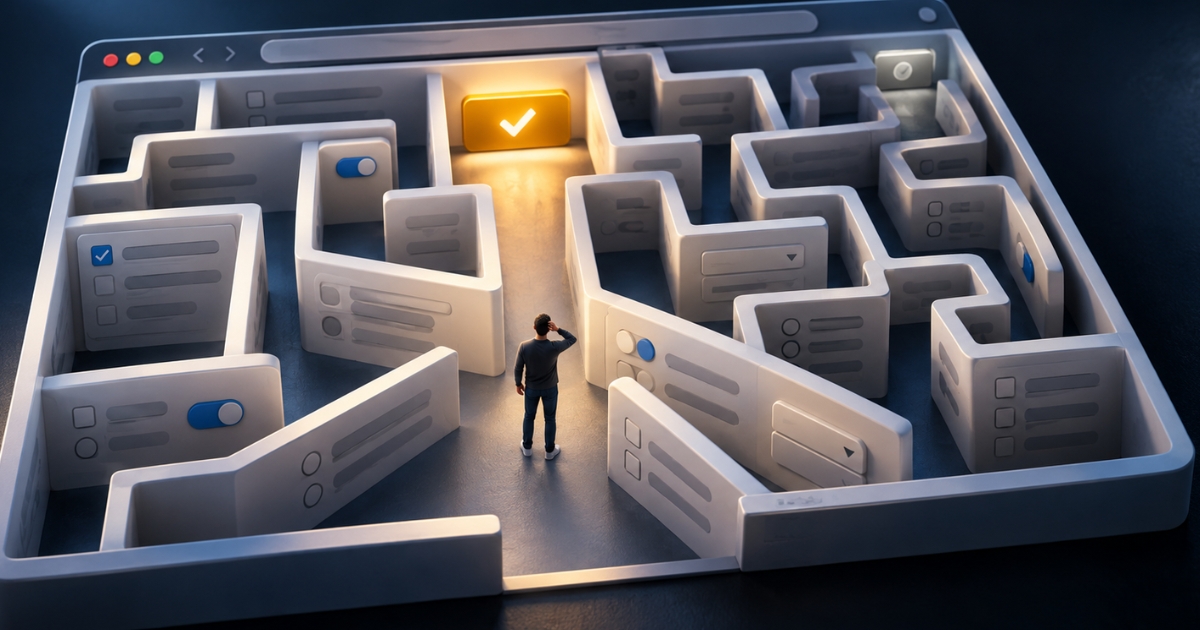
Consider two online services. In the first, both subscribing and cancelling require only a few steps. In the second, subscribing takes a matter of seconds, whereas cancellation requires users to navigate through their account settings, locate a relatively obscure section, proceed through several screens and repeatedly confirm their intention to terminate the service.
In both cases, consumers formally retain the ability to choose. However, in the second scenario, one alternative demands substantially more time and attention than the other.
The term dark patterns refers to interface design practices that deceive or manipulate users, or materially impair their ability to make free and informed choices. However, the mere fact that an interface attracts attention or makes one option more appealing does not, in itself, render it unlawful.
For online platforms falling within its scope, Article 25 of the Digital Services Act prohibits such design practices. Paragraph 2 nevertheless clarifies that this prohibition does not apply to practices already covered by the Unfair Commercial Practices Directive or the General Data Protection Regulation (GDPR). It is therefore necessary to identify the legal framework applicable to the specific conduct under examination.
Paragraph 3 identifies certain practices in respect of which the European Commission may issue guidelines. These include giving greater visual prominence to particular choices, repeatedly requesting users to reconsider decisions they have already made, and making cancellation procedures more cumbersome than subscription procedures.
These examples must be interpreted in light of the general prohibition and its specific scope of application.
The relationship between platform design and behavioural influence was also examined in our article “TikTok, “addictive design” and the DSA: how platform design steers behaviour”.
That analysis focused primarily on infinite scrolling, autoplay, recommendation systems and mechanisms capable of encouraging continued platform engagement. The issue addressed here is somewhat different: it concerns not merely how much time individuals spend on a platform, but how the moment at which they must make a decision is designed and structured.
Comparable safeguards are provided by the Data Act, particularly in relation to access to and use of data generated by connected products and related services.
Article 4(4) prohibits data holders from unduly obstructing users in exercising their choices and rights through the design of digital interfaces. Article 6(2)(a) establishes a corresponding obligation for third parties receiving data at the user’s request.
Recital 38 clarifies the rationale underlying these provisions: users must be able to authorise, refuse or discontinue data sharing without encountering manipulative obstacles.
These rules apply specifically to the legal relationships governing access to and sharing of data within the scope of the Data Act.
What does the Compass Banca case clarify?
The relationship between law and behavioural sciences is illustrated particularly clearly by a significant judgment of the Court of Justice of the European Union (CJEU) delivered on 14 November 2024 in Case C-646/22, Compass Banca SpA v Autorità Garante della Concorrenza e del Mercato.
The dispute arose from Compass Banca’s practice of offering insurance products alongside personal loans, even where the insurance coverage was not necessarily connected to the credit agreement. Although purchasing the insurance policy was not a prerequisite for obtaining the loan, the two products were offered together.
In 2019, the Italian Competition Authority (Autorità Garante della Concorrenza e del Mercato, AGCM) classified this sales practice as an aggressive and unfair commercial practice, prohibited its continuation and imposed an administrative fine.
According to the Authority, the combined presentation of the two products was capable of restricting consumers’ freedom of choice, particularly because the optional nature of the insurance policy had not been made sufficiently clear.
Compass Banca, however, challenged the proposition that the simultaneous offering of two products could, in itself, be regarded as aggressive without concrete evidence of undue influence. The bank also maintained that customers had been informed that the insurance coverage was optional.
Following the dismissal of its initial challenge by the Regional Administrative Court of Lazio (Tribunale Amministrativo Regionale per il Lazio, TAR Lazio), Compass Banca appealed to the Italian Council of State (Consiglio di Stato).
During the appeal proceedings, the Council of State stayed the proceedings and referred several questions to the Court of Justice of the European Union for a preliminary ruling on the interpretation of EU legislation concerning unfair commercial practices.
One of these questions directly concerned the concept of the average consumer. Specifically, the Council of State sought clarification as to whether the benchmark of a reasonably well-informed, reasonably observant and circumspect consumer should also be interpreted in light of scientific findings concerning bounded rationality and the potential influence of cognitive biases.
The Court clarified that the average consumer benchmark remains that established by the Directive. However, this does not preclude the possibility that even a reasonably well-informed, reasonably observant and circumspect consumer may be influenced by cognitive biases.
Consequently, determining how the average consumer would react cannot be reduced to a purely theoretical exercise. The actual circumstances of the case must also be taken into consideration.
This does not mean, however, that identifying a cognitive bias is sufficient to establish that a commercial practice is unfair. It remains necessary to assess whether the practice is capable of materially affecting consumer behaviour in the circumstances at issue.
Following the CJEU’s judgment, the Italian Council of State, in Judgment No. 5901 of 8 July 2025, upheld Compass Banca’s appeal and annulled the contested measures.
The Council of State found that the AGCM had failed to demonstrate adequately the elements necessary to classify the disputed conduct as an aggressive commercial practice.
Nevertheless, a commercial practice may be misleading even where it is not aggressive.
The Court of Justice distinguished between forms of pressure that significantly impair consumers’ freedom of choice and information or presentation methods capable of misleading them.
In the domestic proceedings, no allegation had been advanced on the basis of the latter category. The Council of State nevertheless left open the possibility for the Authority to reassess the conduct, provided that such an assessment was supported by sufficient evidence.
For businesses, the implications are clear: legal compliance assessments must extend beyond the substantive accuracy of the information provided to encompass the entire decision-making process through which consumers are guided.
For consumers, retaining evidence of interface screens, messages and the steps required to accept or reject an offer may prove valuable in reconstructing and substantiating the commercial practice being challenged.
Reviewed by: Arlo Canella
Publication date: 15 October 2026
© Canella Camaiora S.t.A. S.r.l. - All rights reserved.
Textual reproduction of the article is permitted, even for commercial purposes, within the limit of 15% of its entirety, provided that the source is clearly indicated. In the case of online reproduction, a link to the original article must be included. Unauthorised reproduction or paraphrasing without indication of source will be prosecuted.
Martina Di Molfetta
Graduated in Communication, Innovation, and Multimedia from the University of Pavia.